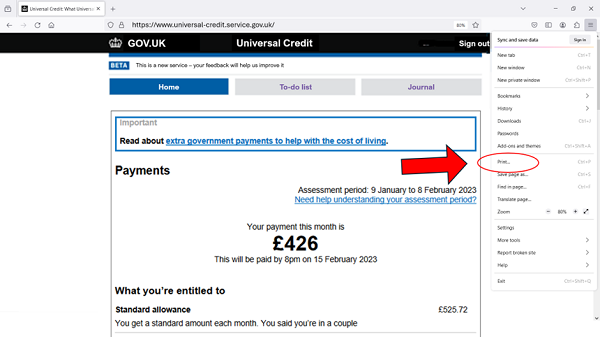
First, take a deep breath. The Department for Work and Pensions (DWP) isn’t running a secret spy operation to judge your late-night biscuit purchases. They want bank statements to check your savings and income are what you say they are. Think of it like a bouncer at a club: they just need to see your ID, not your entire playlist history or that embarrassing photo from 2019. The whole thing is about making sure the numbers on your claim add up to reality—and that you’re not secretly a millionaire hiding cash under a mattress made of gold bars.
I remember a mate of mine, Sarah, who panicked so hard she printed off six months of statements and highlighter-ready for a whole afternoon. She even circled a £1.50 donation to a charity—like, “Look, I’m a good person, don’t cut my benefit!”. In the end, the caseworker just glanced at her savings total and said, “You’re fine, love. We just needed to see it.” It was anticlimactic, like waiting for a thunderstorm that turns into a light drizzle.
The Real Reason: It’s All About Fairness (and the Law)
Universal Credit is a means-tested benefit, which is a fancy way of saying “we’ll pay you based on what you actually have, not what you wish you had.” If you’ve got more than £16,000 in savings, you’re generally not eligible. If you’ve got between £6,000 and £16,000, the amount they pay you goes down a bit. So, the bank statement is the proof of that pot of money. Without it, the system would be like trying to bake a cake without knowing how much flour you have—you’d probably end up with a sticky mess that looks sad and doesn’t work.
But there’s another layer. They also want to see your regular income—wages from a job, self-employed earnings, odd bits of cash. This is because Universal Credit adjusts each month based on your actual pay, not some guess from last year. It’s like having a flexible gym membership: you pay for what you use, not a fixed fee that ignores you skipped leg day for three months. So if you do a shift at a pub and earn £150, that shows up. And the system recalculates your UC payment accordingly, which is actually pretty smart once you get past the initial “they’re watching my every move!” feeling.
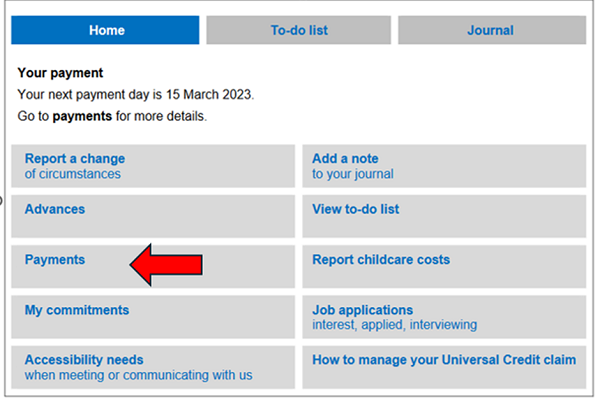 Getting claim information and statements from your online universal
Sure, it feels invasive. “Why do you need to see that I spent £4.99 on a cat calendar in January?” you might grumble. But the DWP isn’t zooming in on that purchase. They’re looking at the overall pattern: is there a sudden deposit of £5,000 from an unknown source? Did you win the lottery and forget to mention it? Most of the time, your statement is just a long list of boring transactions—petrol, groceries, the occasional Netflix charge—that adds up to a normal life. And that normal life is exactly what they need to see to confirm your claim is accurate.
What If You “Accidentally” Forget?
Here’s the thing: ignoring the request is like ignoring a polite tap on the shoulder in a library. It only gets louder and more awkward. If you don’t provide the statements, the DWP will eventually pause or stop your claim. They can also reduce your payment to the absolute minimum—which is their way of saying, “We tried to play fair, but you didn’t play along.” There have been stories of people losing thousands of pounds because they thought “I’ll send them next week” and then forgot for three months. That week turns into a month, and suddenly you’re living off toast and hope.
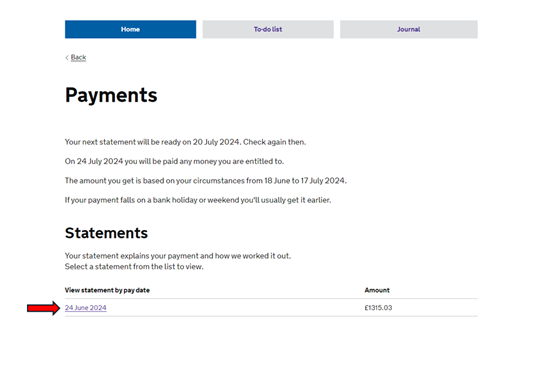 Getting claim information and statements from your online universal
So here’s my advice: treat the bank statement request like a dentist appointment. It’s a bit of a chore, you might feel a little vulnerable, but it’s over quickly and it prevents a bigger headache later. You can upload the statements directly into your online UC journal (take a photo with your phone—no need to dig out a scanner from 2005). Redact any non-essential info if you’re feeling paranoid, but don’t black out the transactions they need. It’s like going to a job interview: you don’t wear your best suit, but you also don’t show up in pajamas. A clean, clear statement does the trick.
And remember the big picture: Universal Credit is designed to catch people, not punish the honest majority. Most of us don’t have secret offshore accounts or a stack of cash under the sofa. We’re just trying to get by, one boring bank statement at a time. So next time you get that request, take a breath, grab your phone, and submit those statements with the confidence of someone who knows their last ten transactions are just a desperate mix of cat food, bus fares, and a single cheeky chocolate bar. You’ve got this. The system is just having a little peek, not writing a biography.

