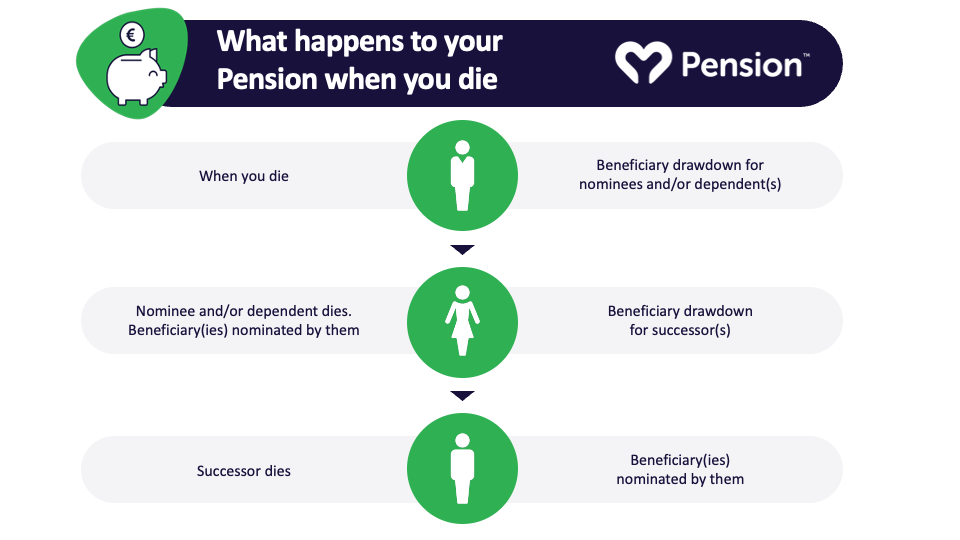
First, a fun fact: your pension isn’t a single lump of cash under a mattress—it’s more like a subscription to a streaming service that pays you monthly. If you pass away before collecting a dime, the rules change depending on whether you have a defined benefit plan (classic employer pension) or a defined contribution plan (like a 401(k) or IRA). Think of it as the difference between a vintage vinyl collection and a Spotify playlist—one is curated by a company, the other is all yours.
In most cases, your pension doesn’t just vanish—it goes to a beneficiary you’ve named, or to your estate. But here’s the kicker: if you’re single and die before retirement, your defined benefit plan often keeps the money, like a canceled subscription. That’s why naming a beneficiary is your golden ticket.

