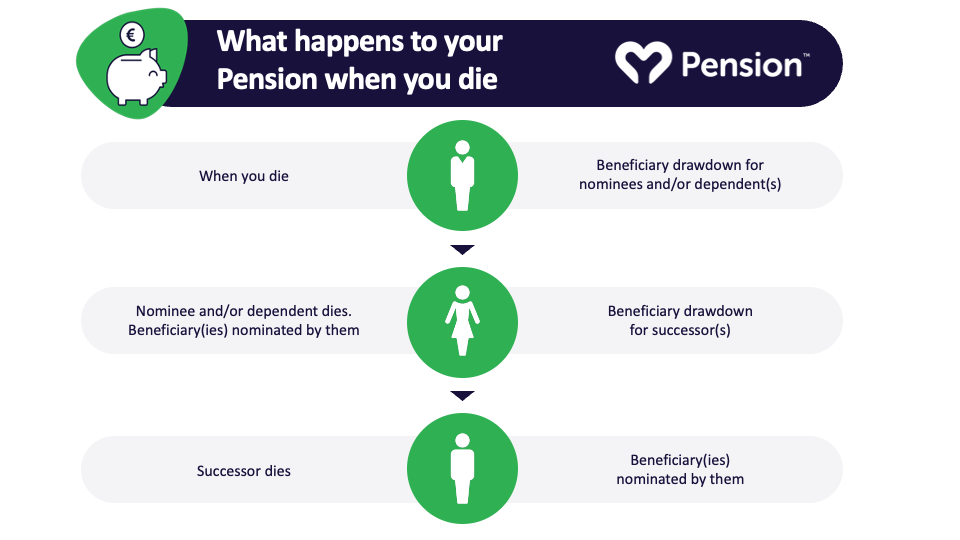
First, you gotta know there are two main types of pensions: defined benefit (the old-school gold watch kind) and defined contribution (your modern 401k-style pot). They react totally differently when you die—kind of like cats versus dogs.
With a defined contribution plan, that pot is your money. It’s basically a giant savings account with tax perks. When you die, whatever’s left passes to your beneficiaries—usually your spouse, kids, or whoever you named.
But a defined benefit plan? That’s more like a rental agreement with your employer. You get a monthly check for life, but the leftover cash doesn’t automatically go to your heirs. Cool, right? It depends on how you set it up.
Spouse, Kids, or Stranger: Who Gets the Goods?
Here’s where it gets interesting. Most pensions let you choose a survivor benefit option when you retire. Think of it like ordering pizza: you can pick the “single life” option (cheaper monthly slices, but they stop when you’re gone) or the “joint life” option (smaller slices, but your spouse keeps eating after you’ve left the table).
If you go with joint life, your partner gets a percentage—often 50% to 100%—of your pension forever. Forever. That’s like a secret handshake that outlives you. Pretty rad, right?
But what if you’re single or your kids are grown? You might not care about survivor benefits. In that case, you can take the bigger monthly check and blow it all on travel. Your pension dies when you do—no leftovers.
PPT - Pension Seminar for non-teaching pension plan members PowerPoint