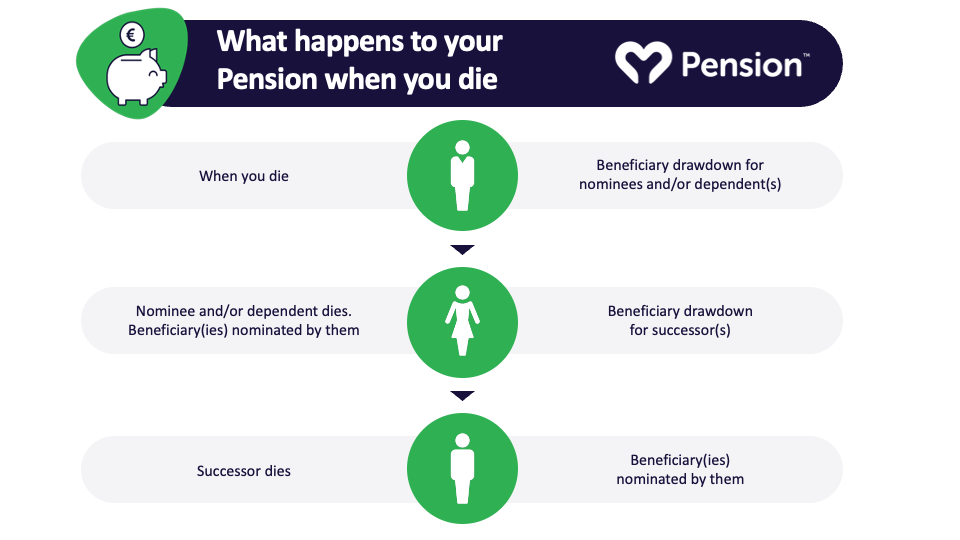
First, we need to talk about which flavor of pension you have, because your death treats them very differently. Think of it like this: a Defined Benefit pension is a grumpy old cat—it promises you a steady stream of fish (money) for life, but once you die, the cat might stop purring. A Defined Contribution (like a 401k or a personal pot) is more like a bucket of cash with your name on it—whoever you leave the bucket to gets to drink from it.
If you have the old-school "final salary" pension (the grumpy cat), your monthly payments usually stop when you die. Surprise! The pension plan isn't a charity for your heirs—it's a deal for you. Unless you picked a survivor benefit, your spouse might get a reduced payment, but your freeloading nephew? He’s getting zero.
The "Joint Life" Option: Your Spouse Gets a Crumpled Coupon
Here’s where it gets juicy. Many pensions let you take a lower monthly payment now, so your spouse gets something after you’re gone. It’s called a joint and survivor annuity. You take a haircut on your own income—sometimes 10% or 20% less—so your partner gets 50% to 100% of your payment for life. It’s like saying, “Honey, I love you, but I’m going to die first, so here’s half my sandwich.”
The hilarious catch? If you die before your spouse, they get that money. But if they die first? You just paid for a benefit you’ll never use. It’s like buying a fire extinguisher for a house that never catches fire—fiscally responsible, but slightly annoying.

