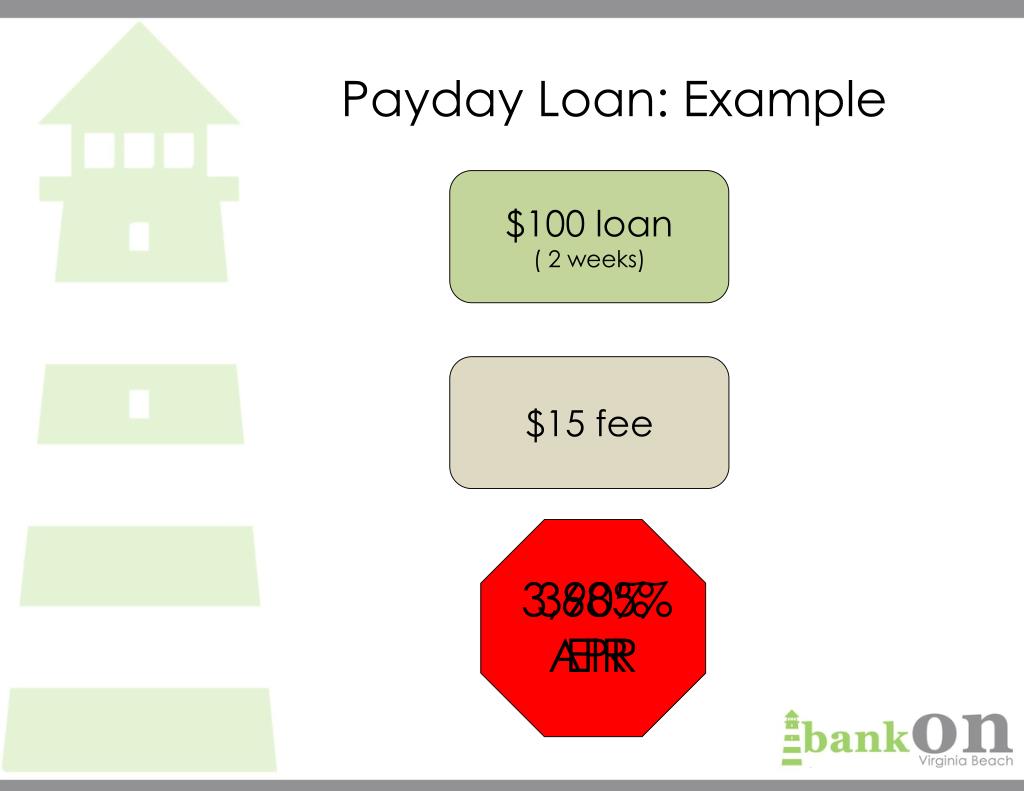
So, how do these payday lenders operate? Well, it's pretty straightforward: you apply for a loan, and if you're approved, you get the cash you need, usually within a day or two. The catch is, you'll have to pay back the loan, plus interest and fees, when your next paycheck arrives - hence the name "payday lender". It's like borrowing from a financial friend, but with more formal agreements and, of course, interest rates.
Now, you might be wondering, what's the big deal about payday lenders? Aren't they just like regular banks or credit unions? Not exactly, because payday lenders specialize in high-risk, short-term loans that traditional banks might not touch. It's like they're the financial rebels, catering to people who need help quickly, without all the red tape and strict requirements.
But, as with any financial transaction, there are pros and cons to consider. On the one hand, payday lenders can provide emergency funding when you need it most. On the other hand, those interest rates and fees can add up quickly, making it tough to pay back the loan. It's like playing a financial game of Jenga - you gotta be careful not to knock over the whole tower.
 Best Small Payday Loans Online - BadCredit.org

