
The big deal is that they can affect everything from mortgage rates to credit card rates. Think about it like this: when interest rates are low, it's like getting a discount on the money you borrow - you can get more house for your buck, or afford more stuff on your credit card. But when rates are high, it's like getting a surcharge - you'll pay more for that same house or credit card purchase.
Now, you might be wondering how Florida interest rates compare to the rest of the country. Well, let's just say that Florida is a bit of a unique snowflake - its interest rates are influenced by the state's booming tourist industry, as well as its growing population. This means that Florida interest rates can be a bit more volatile than other states, but also more opportunistic for borrowers.
So, what does this mean for you? If you're thinking about buying a house or refinancing a loan in Florida, you'll want to keep a close eye on those interest rates. It's like waiting for the perfect wave to catch - you want to time your loan application just right, so you can ride the wave of low interest rates and save some serious cash. But don't worry, it's not as complicated as it sounds - just think of it like a fun game of interest rate limbo: how low can you go?
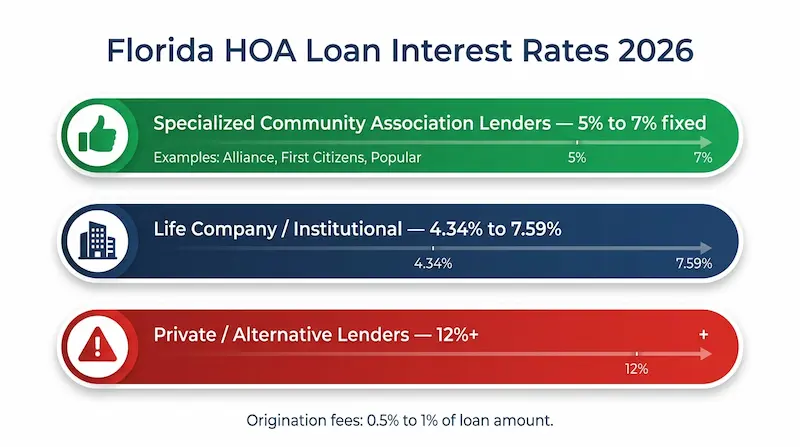 How to Get an HOA Loan in Florida 2026

