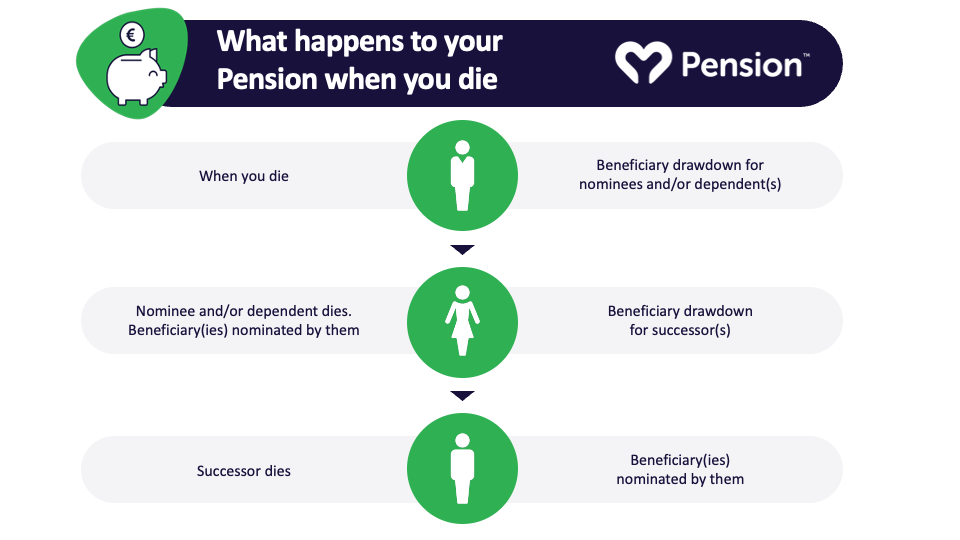
Now let’s talk about defined contribution plans—things like 401(k)s, IRAs, or a pot of money you built yourself. This is the good stuff. You own the account, and whatever’s left when you die belongs to your beneficiary. It’s like leaving a treasure chest with a sticky note that says, “Enjoy, but I ate the chocolate first.”
 What happens to my pension when I die - National Pension Helpline
Your spouse, your kids, or even your pet iguana (if you named them as a beneficiary) can inherit this money. They can roll it into their own retirement account, take it as a lump sum, or—if they’re feeling wild—buy a lifetime supply of pickles. The key is to name a beneficiary. If you don’t, the government might step in and decide for you, and trust me, they’re terrible at choosing music for your funeral.
The “Oops, I Forgot Again” Twist (This One’s a Doozy)
If you’ve got a 401(k) but never named a beneficiary, the money might go to your estate—which means it goes through probate court. Probate is like a slow-motion car crash for your savings. It takes forever, costs money, and your loved ones will be pulling their hair out. So please, for the love of spreadsheets, fill out that beneficiary form. It takes five minutes, and it’s way easier than explaining to your ghost why your kids are crying over paperwork.

